Industry: Fintech / Financial Services
At a glance: MyntiQ Tech built a real-time AI risk and fraud engine for a private equity-backed digital lender. It scores borrowers with alternative data such as cash flows and utility history, and detects fraud with device fingerprinting and behavioral biometrics. It returns decisions in milliseconds and automates over 85% of them.
Overview
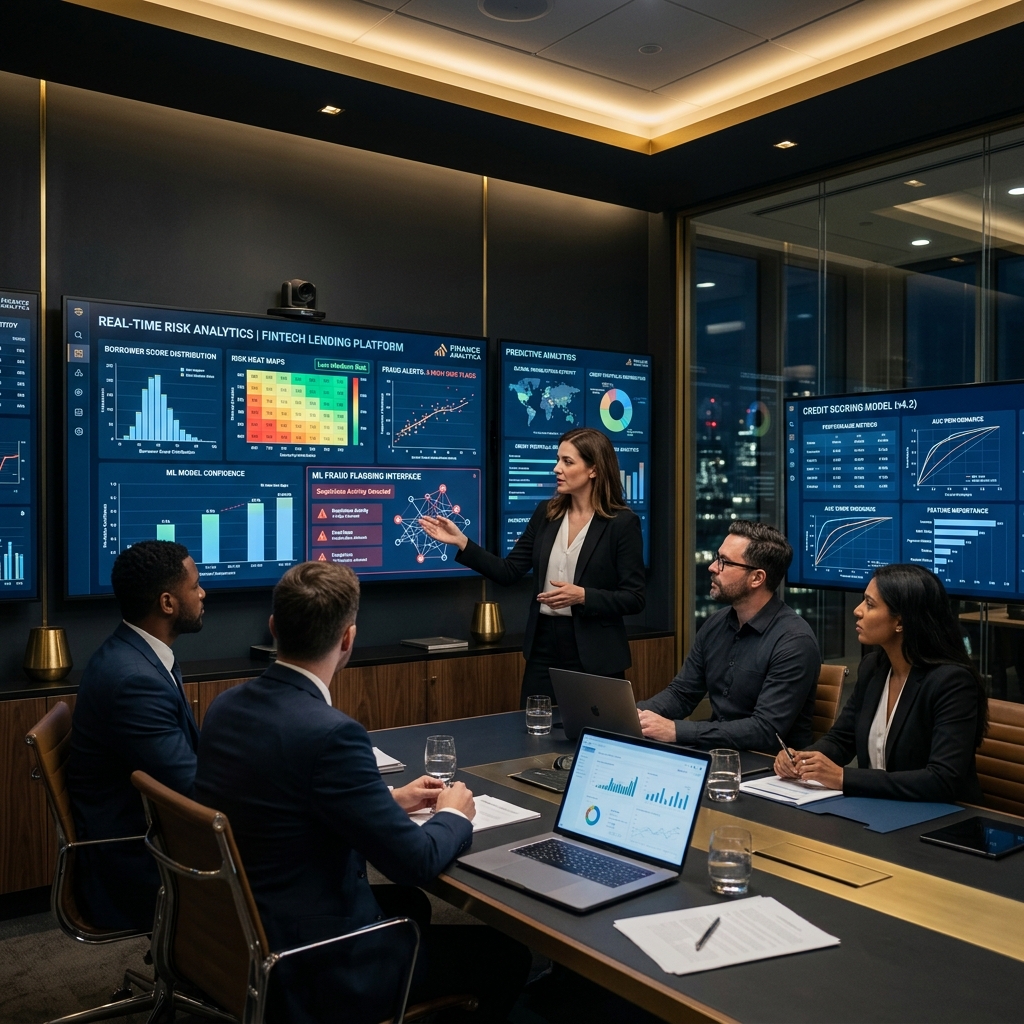
This case study details the deployment of an AI-driven risk modeling and real-time fraud prevention engine for a private equity-backed digital lending platform. By applying machine learning to multi-source financial data, the system flags fraudulent applications and calculates borrower risk profiles instantly.
Business Problem
The lending platform was constrained by high risk metrics:
- Traditional, static credit scoring locked out credit-worthy borrowers with thin files, limiting user growth.
- The platform was targeted by sophisticated loan application fraud, causing financial write-offs.
- Manual underwriting reviews created transaction bottlenecks, causing customer drop-off.
How MyntiQ Tech Helped
MyntiQ Tech built a smart underwriting and security framework:
- Advanced Risk Assessment: Trained machine learning models on alternative data sources, including transactional cash-flows and utility histories, to assess borrower risk accurately.
- Behavioral Fraud Detection: Integrated device fingerprinting, behavioral biometrics, and IP verification to flag automated bots and stolen identities.
- Real-Time Decisions: Built an API engine that processes application queries in milliseconds, approving low-risk users instantly.
Business Outcomes Delivered
- Reduced loan default rates significantly, protecting capital assets.
- Increased applicant approval rates without raising overall risk exposure.
- Identified and blocked fraudulent loan applications, saving millions in potential write-offs.
- Automated over 85% of decisions, speeding up customer access to credit.
Frequently Asked Questions
How can AI score borrowers with thin credit files?
Machine learning models trained on alternative data, such as transactional cash flows and utility payment history, assess risk for borrowers that traditional credit scores lock out.
How does a digital lender detect loan application fraud?
Device fingerprinting, behavioral biometrics and IP verification flag automated bots and stolen identities before an application is approved.
How fast are credit decisions?
The API decision engine processes applications in milliseconds, approves low-risk applicants instantly, and automates over 85% of decisions.
Building lending or fintech AI? Talk to MyntiQ Tech or browse more case studies.